
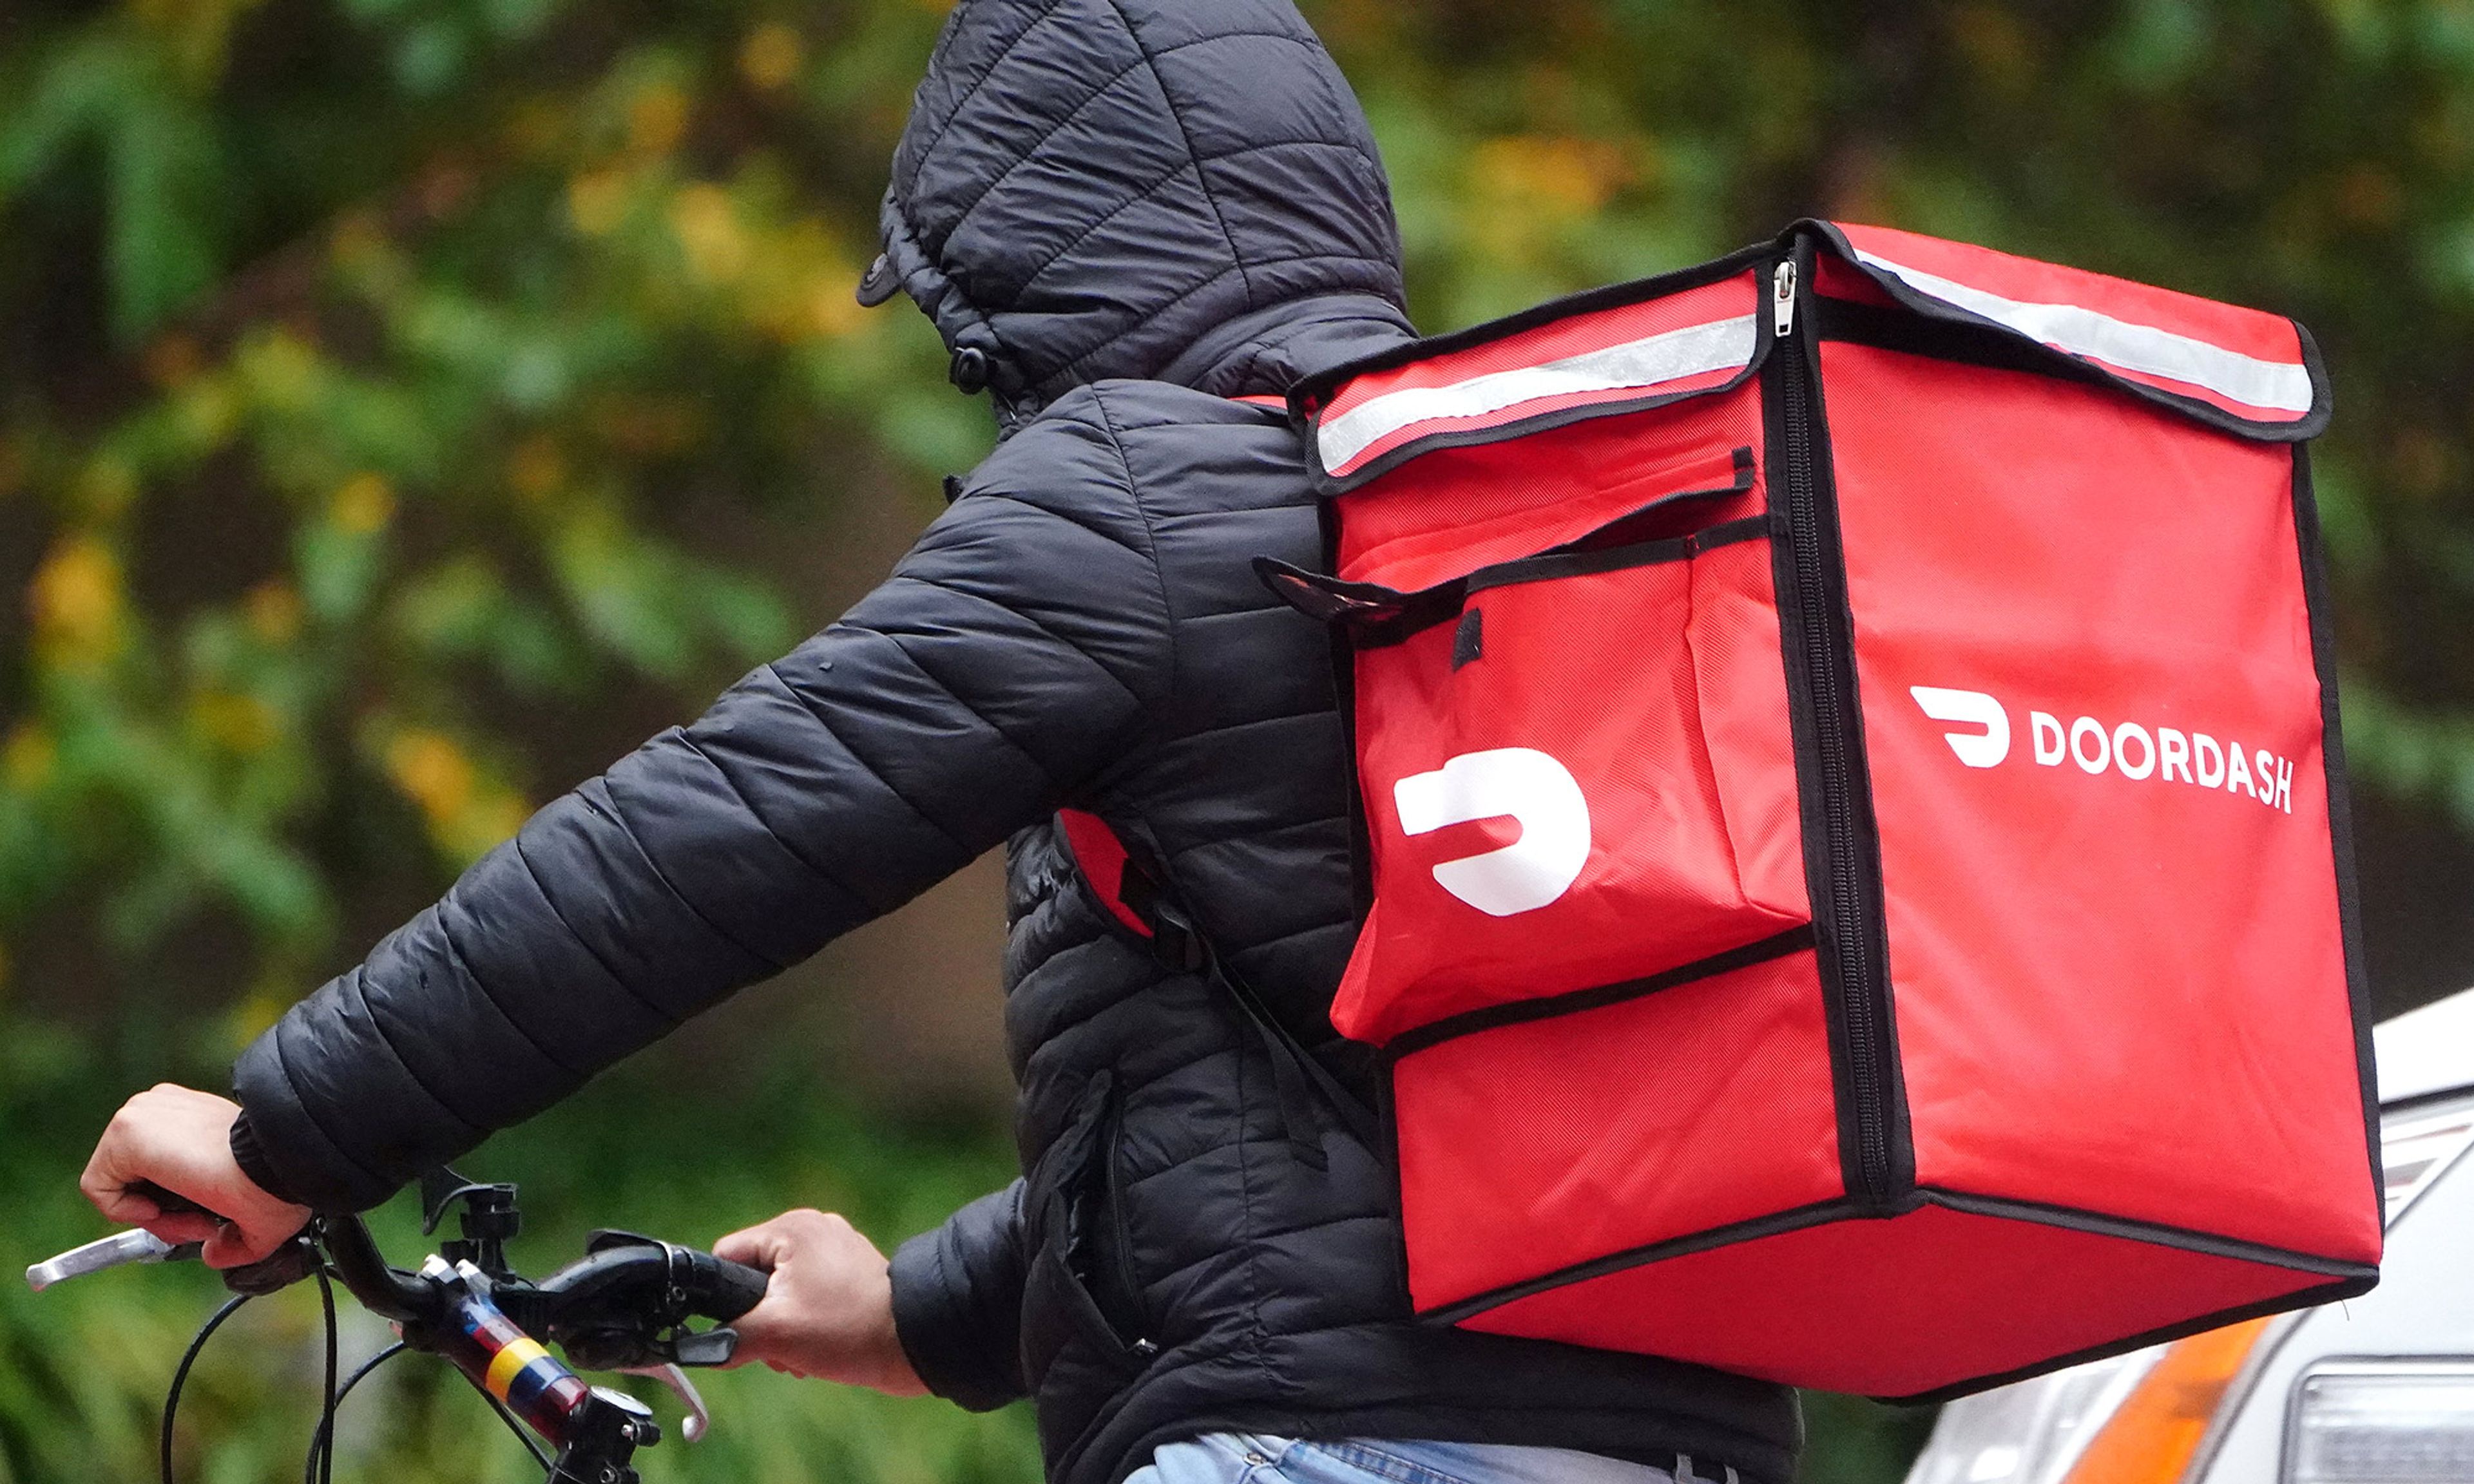
There are good ideas, there are bad ideas, and there is working with DoorDash and Klarna to finance your Cheesy Gordita Crunch.
Klarna, the buy now, pay later lender that’s headed for an initial public offering, said on Thursday that it’s signed on DoorDash as a partner, another sign of momentum for public market investors.
It’s DoorDash’s first BNPL alliance in the U.S. and gives users of the restaurant delivery service a new way to pay for meals and products. Klarna said in a press release that DoorDash customers will be able to pay in full at checkout, split payments into four equal interest-free installments, or defer to dates that align conveniently with payday schedules.
Look, I have some sympathy for the young and the cash-strapped when it comes to these kinds of things. It wasn’t that long ago that I was young and cash-strapped myself. It wasn’t that long ago, back in college, when I found myself racking up a couple grand in credit-card debt. (The pitchers of Irish Red and the spicy honey wings at O’Connell’s in Norman were cheap — but they weren’t free.)
But a big part of getting a real job and growing up was getting the pretty basic idea through my thick skull that financing frivolous consumer expenses like eating out was a simply terrible idea. Some people learn this the easy way; some people learn it the hard way. I’d say I was more in the latter camp. It took me a while — i.e., longer than it should have — but I learned that through saving and paying all that off, student loans included, and by learning to live on a budget, not only was life not more constricting, it was liberating. I was finally free.
Back in the fall, I remember reading that the Bureau of Labor Statistics found that, while Americans spend about what they did in 1950 on food prepared at home (adjusted for inflation), we spend a huge amount more eating out. The average American spends something like $3,900 in restaurants per year. And that number has grown more than 20 percent in recent years.
In principle, I don’t have an issue with that: America is an extraordinarily wealthier country today than it was in 1950. If people have the money, who am I to tell them how to spend it?
But the fact that DoorDash is opening up exciting new financing opportunities for a take-out taxi service indicates that things have spun out of control for a whole lot of people.
Let’s face it: If you can afford to eat out, you don’t need to break up your pad Thai into four easy, interest-free payments. If you can afford a takeout Rueben sandwich, you don’t need the option to conveniently defer your payments to your payday schedule.
And despite the breathless — and embarrassing — coverage on CNBC for this monstrosity of an IPO, everyone with the minimum of amount of sense should realize that those easy-peasy interest-free installments are certain to get converted into shockingly expensive usury should you miss a single payment.
This is exploitation. It’s taking advantage of people who don’t know any better, even if they should.
Shun it. Shame it. Scorn it. And tell your friends: Don’t finance your burrito bowls.

Comments