
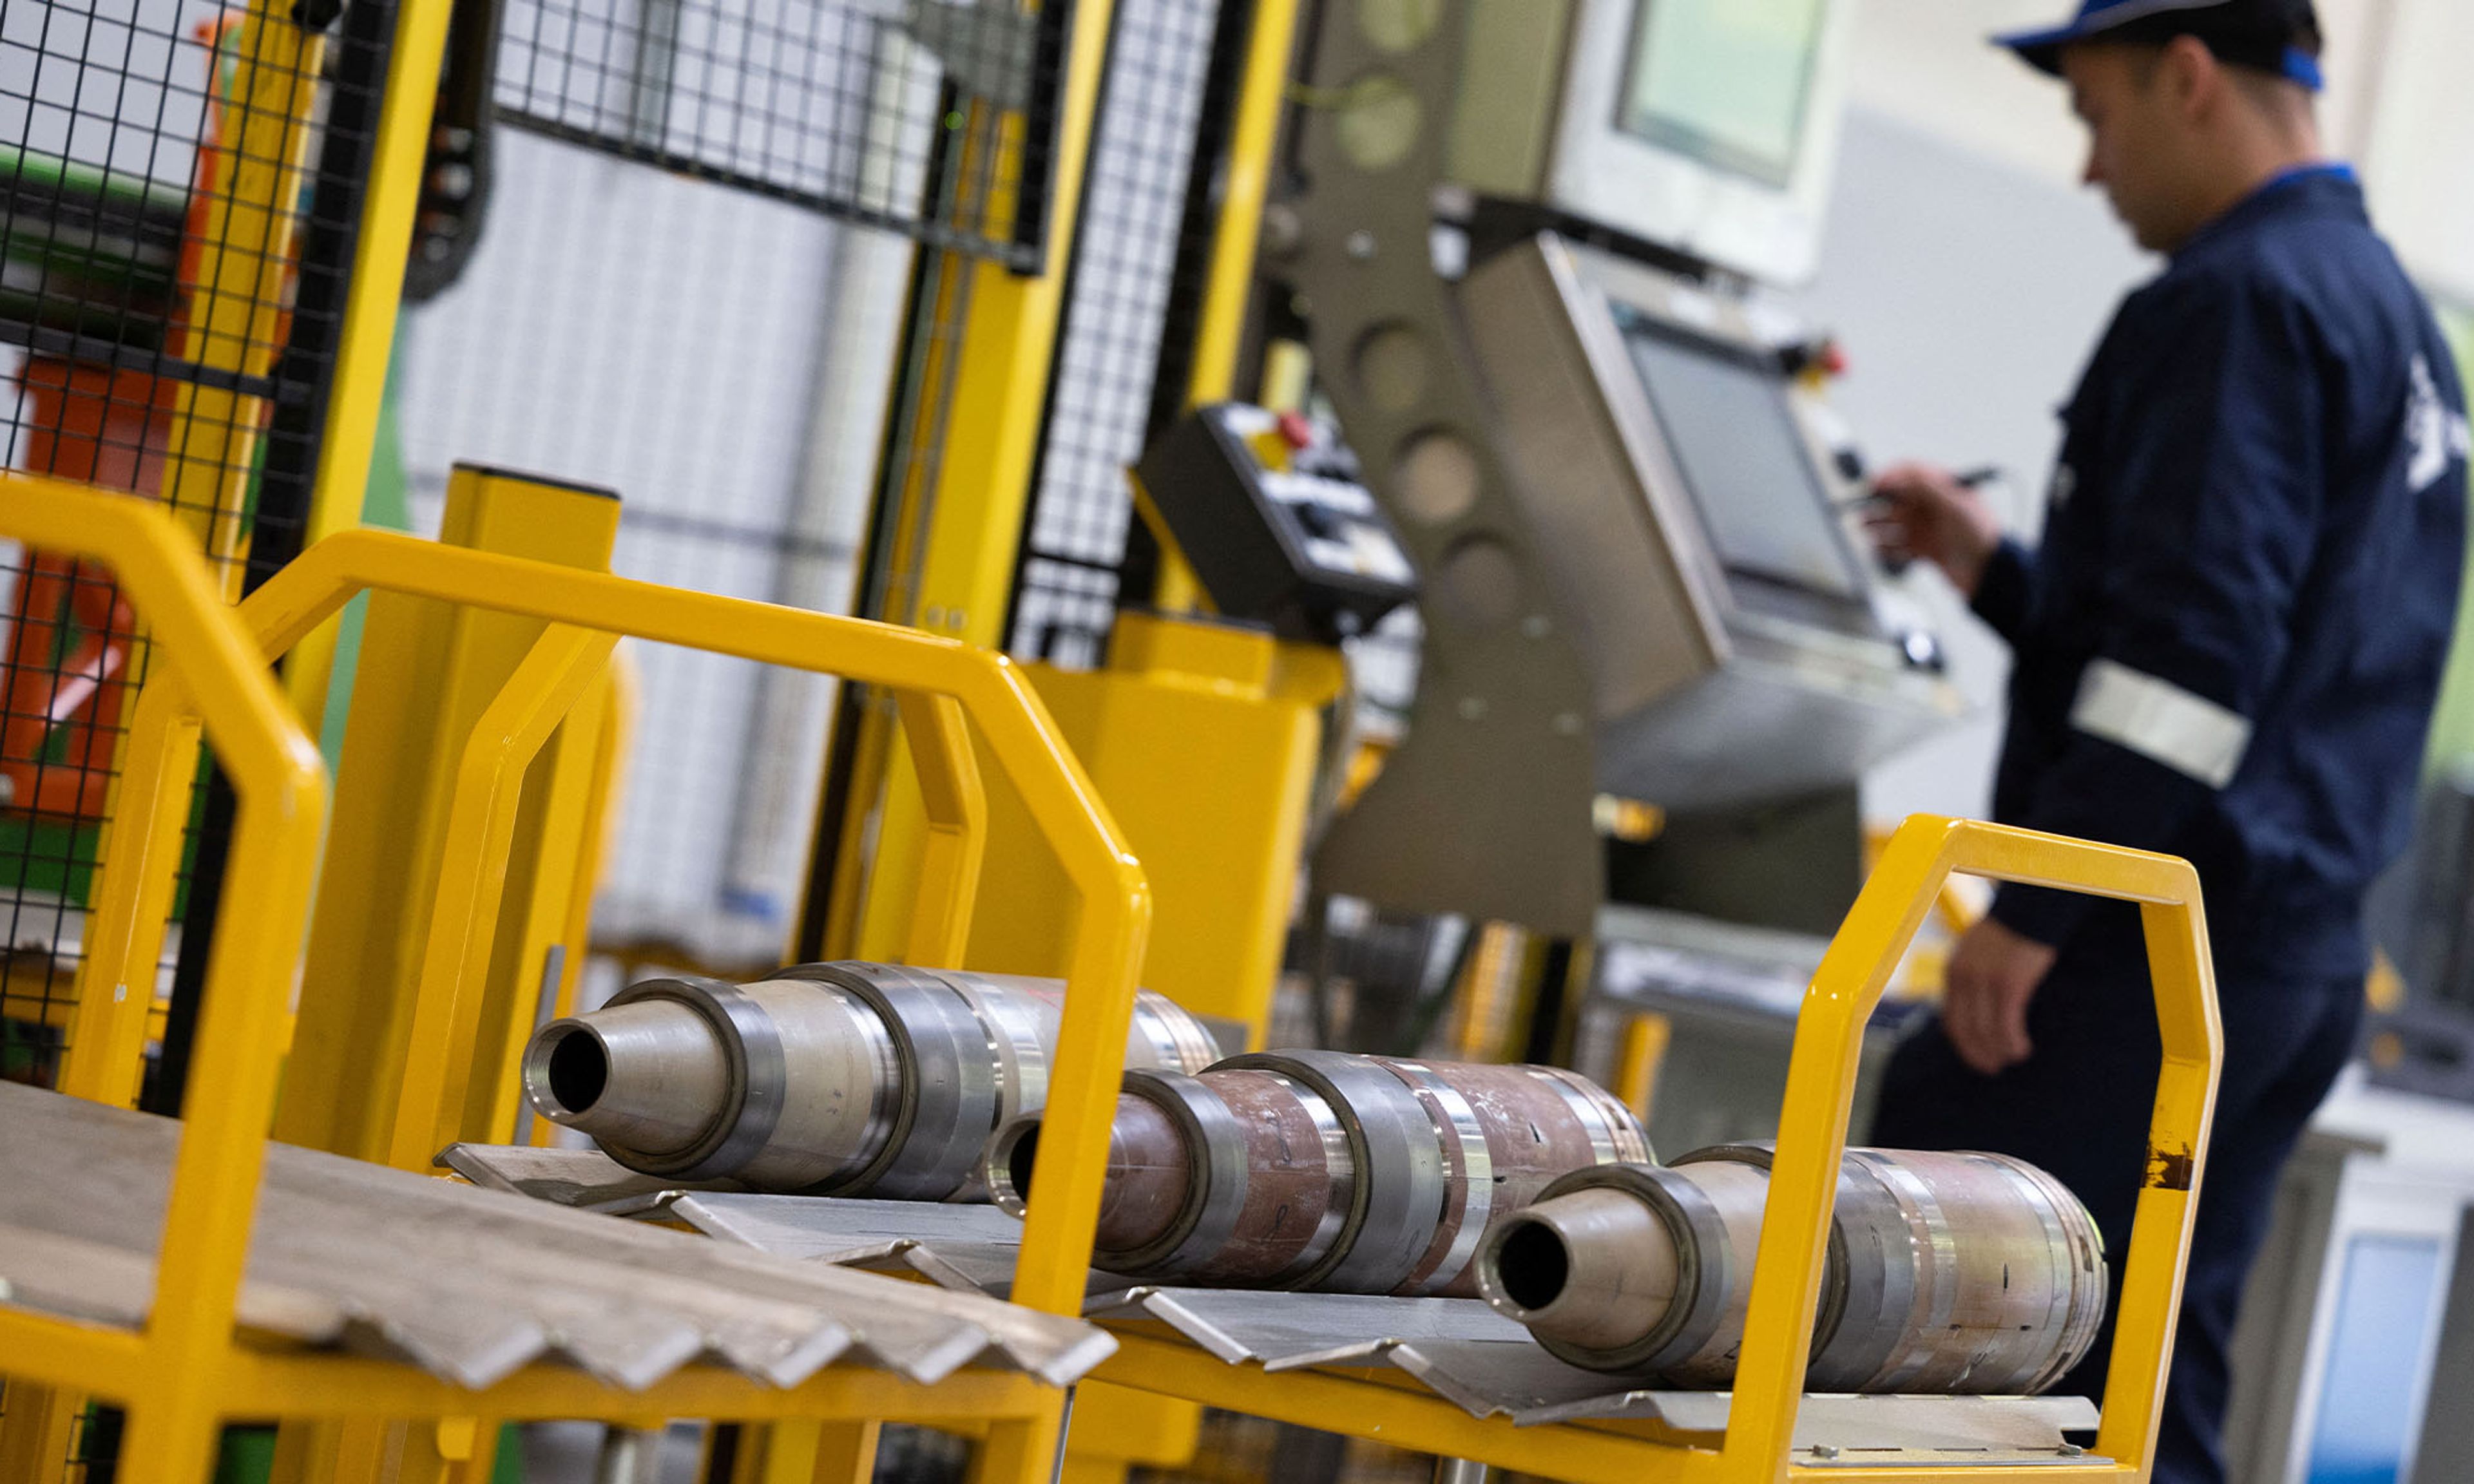
ESG was — and is — a bogus investment “discipline,” but there is nothing bogus about the damage for which it has been responsible. That included, particularly in Europe, the way that investments in the defense sector were hard to squeeze into ESG’s straitjacket, not great at a time when Putin was already on the march.
In an article for Bloomberg in March 2022, Lisa Pham wrote, “The arrival of war in Europe has some investment clients questioning whether money they’ve put toward environmental, social and governance goals is being well spent, according to [Jean-Xavier Hecker,] the co-head of ESG equity research at JPMorgan Chase & Co.”
It took a war for these clients to start questioning that? Oh well.
Pham went on to write how the war in Ukraine had triggered a debate over the way that “the ESG industry should respond.” She explained:
Defense lobbyists have said regulators in the EU should start treating weapons as ESG-friendly because they can be tools for defending democracy. Critics have countered that that misses the obvious point that guns and bombs are ultimately responsible for millions of deaths.
Note the framing: “Defense lobbyists” against “critics.”
Pham also added that “there are growing fears that Russia’s war on Ukraine is derailing the fight against global warming.” I am sure that they were talking of nothing else in Kyiv.
JPMorgan’s Hecker did not think that defense stocks would become serious contenders for ESG portfolios, arguing that the “fundamental approach of why defense wasn’t in ESG funds hasn’t changed.”
Fast forward to mid-2025 and there had been a shift. According to Morningstar’s Sustainalytics, within the EU “Article 8” funds (funds that take ESG factors into account, without being specifically dedicated to “sustainable” investment) had roughly doubled their exposure to aerospace and defense stocks, even though they remained underweight when compared with unfettered “Article 6” funds. Even deep green “Article 9” funds had room for defense stocks, but their overall exposure to them had not changed over earlier years.
Apart from their role as a source of fees and other revenues for the rentseekers in its ecosystem, ESG and its symbiont stakeholder capitalism are best seen as corporatist devices for a technocratic elite to advance a social and economic agenda without going through the bother of legislative approval.
It was thus unsurprising to read that:
Under pressure from clients and politicians, asset managers are revising their weapons exclusion policies to allow investments in certain types of weapons. For example, Allianz Global Investors has removed exclusions for its Article 8 mutual funds in two specific areas: military equipment and services and nuclear weapons permitted under the Non-Proliferation Treaty. Similarly, UBS Asset Management withdrew its policy prohibiting its sustainable funds from investing in companies that generated more than 10% of their revenues from producing conventional military weapons. Meanwhile, Danske Bank Asset Management removed approximately 30 defense-related companies from its exclusion lists.
It is easy enough to see why clients might want that. The MSCI Europe Aerospace and Defense index has massively outperformed the broader MSCI Europe index over the past three years. However, the involvement of politicians is a reminder that ESG is designed to serve societal interests (as interpreted by the right people) rather — whatever the claims of its promoters — than those of investors, although in this case investors will have benefited. And, yes, on this occasion the politicians were on the right side too.
At the end of December, the EU Commission, the Financial Times reported, published a notice clarifying what types of defense investment met its “sustainability” requirements. Some confusion had been created by an imprecisely defined prohibition on “controversial weapons.” According to the FT’s Bryce Elder, the “vagueness was unhelpful for the EU’s target to raise €800bn in defense investments over four years.” “Controversial” was replaced by “prohibited,” a category that comprises personnel mines, cluster munitions, biological and chemical weapons, but not companies that handle white phosphorous or depleted uranium or . . .
Wait for it.
“Atomic bombmakers get a pass.”
Meanwhile (and understandably enough):
WARSAW, Dec 17 (Reuters) — Poland has decided to start producing anti‑personnel mines for the first time since the Cold War and plans to deploy them along its eastern border and may export them to Ukraine, the deputy defence minister told Reuters.
Joining a broader regional shift that has seen almost all European countries bordering Russia, with the exception of Norway, announce plans to quit the global treaty banning such weapons, Poland wants to use anti-personnel mines to beef up its borders with Belarus and Russia.




Comments