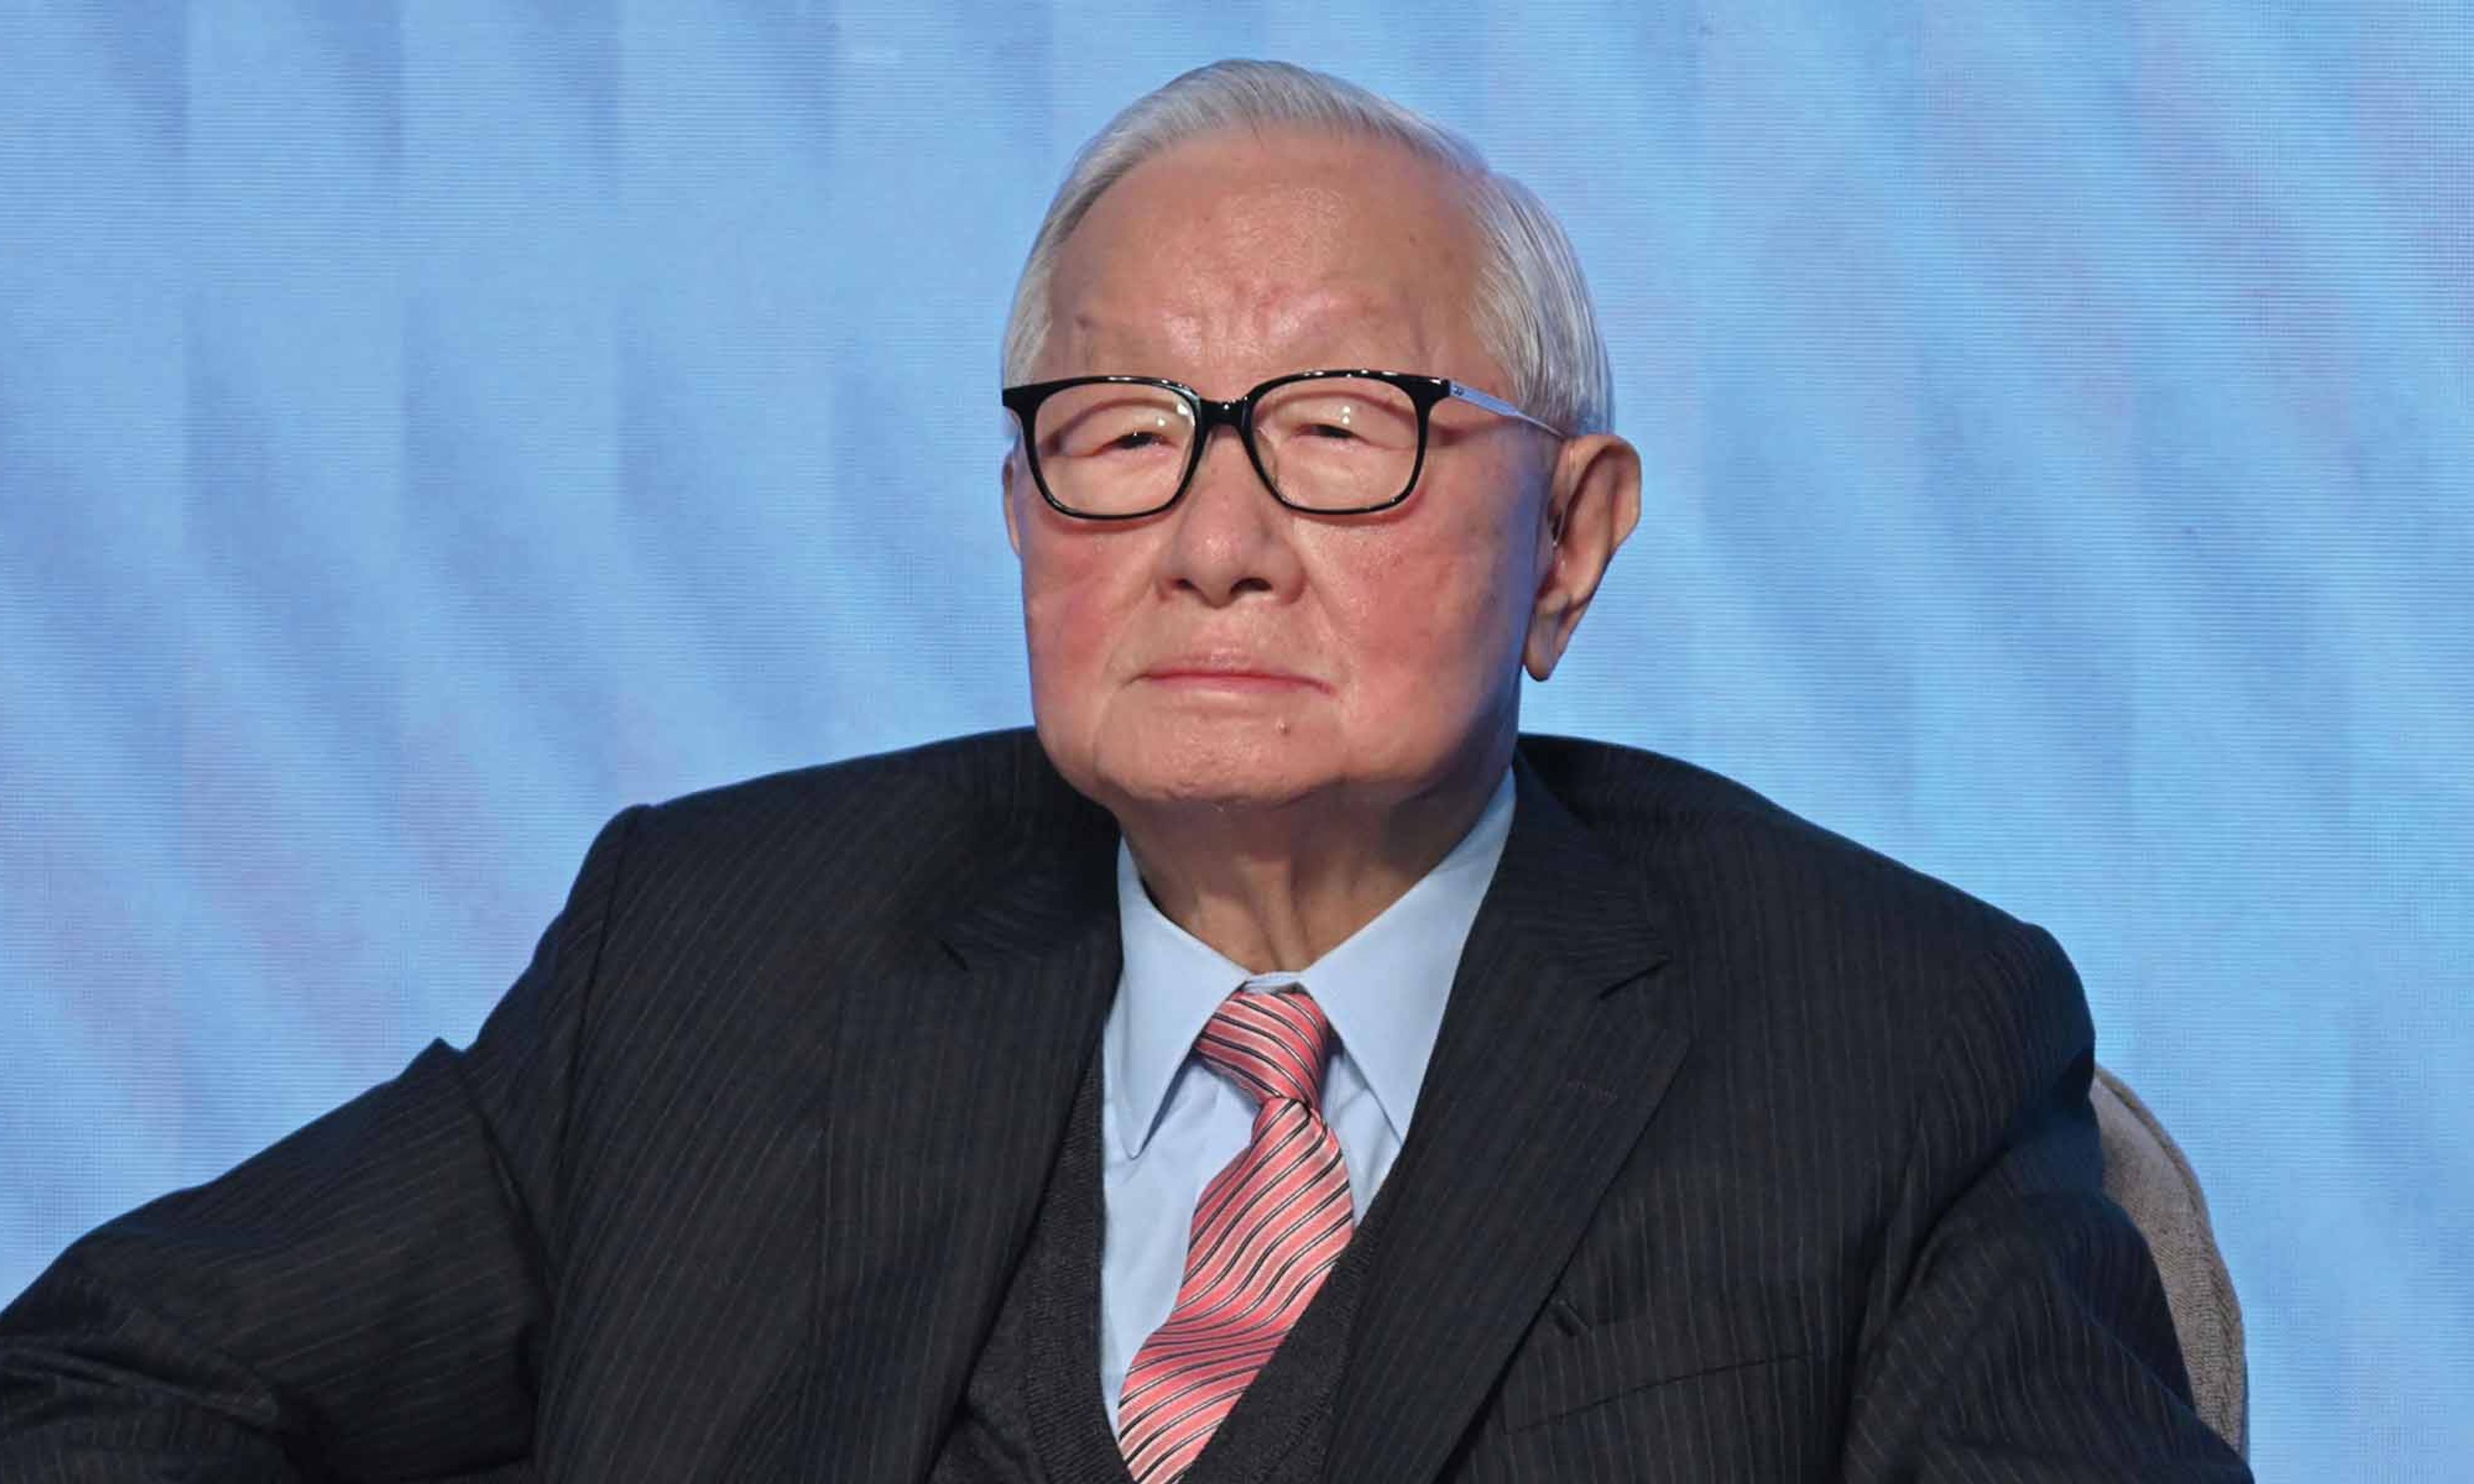
With Senator Mark Kelly at his hip, President Joe Biden flew to Arizona in December to commemorate the latest investment by the Taiwan Semiconductor Manufacturing Company (TSMC) in the Grand Canyon State. Standing at the site of a Phoenix plant that will produce wafers for the company’s namesake technology, the president shook hands with TSMC chairman Mark Liu and founder Morris Chang, declaring in his signature style that American manufacturing “is back, folks.”
TSMC is the world’s undisputed champion in the production of the leading-edge logic chips that power the modern world. Its contract foundry business model — you send them a design, they make it — has enabled it to outpace all rivals in the ability to produce custom chips at scale for everything from consumer electronics to cars to telecommunications kits to fighter jets. TSMC’s Taiwan plants (“fabs,” in industry lingo) churn out an astonishing 90 percent of the world’s most advanced processor chips.
The Arizona plan that TSMC unveiled in December allocates $40 billion to expand and upgrade a U.S. production facility, on Phoenix’s northern fringe, that TSMC says will eventually produce the three-nanometer chips that currently represent the state of the art and supply such prized customers as Apple. According to Liu, this fab and another slated to open in the state by 2026 will create 13,000 high-paying jobs, including 4,500 directly with TSMC.
The flurry of chip activity in Arizona is the culmination of the state’s half-decade courtship of the industry, which has included trips to Taiwan by recently termed-out Governor Doug Ducey, a lead negotiating role for Senator Kelly in securing the passage of the CHIPS Act in Congress in summer 2022, and generous financial incentives from the state capitol and Arizona’s various municipal governments. Specifically, the state is spending $100 million to spur growth in what the Arizona Commerce Authority calls “a critical sector of its economy,” has enlisted companies in the semiconductor industry to write curricula at community colleges, and has shown TSMC that, in the words of one Arizona insider, the state has “government, academia, and industry all rowing in the same direction.”
The city of Phoenix has agreed to provide TSMC with $200 million in infrastructure incentives, including water lines, sewage, and roads, with one traffic light expected to cost the city a whopping $500,000. The city of Chandler has in place similar policies favoring American chipmaker Intel, including $30 million in water and road improvements for its two plants under construction. Arizona State University, meanwhile, spent more than half a million dollars in 2022 to lobby for a federal commitment to chips that it sees as key to its own growth strategy.
While the $52 billion of semiconductor subsidies provided by the federal CHIPS Act adds vital fuel, Arizona is crafting state and local industrial policy of its own that it thinks will put its economy at the forefront of American prosperity. The state has homed in on semiconductor manufacturing, selected it for favorable treatment, and hitched its wagon to the industry’s rise. In its industrial aspirations, Arizona has a role model in Taiwan itself, where TSMC has proven a world-historical success in industrial policy.
But just as Arizona has launched its effort to become “a global hub for microelectronics,” warning signs portend a repeat of past industrial-policy misfires in the United States.
For industrial-policy boosters, few examples provide better supporting evidence than Taiwan, one of the small East Asian economies referred to in Chinese as “the Four Little Dragons,” for their spectacular rise in the second half of the 20th century. While the city-states of Hong Kong and Singapore offer their own lessons, the country-sized economies of Taiwan and South Korea arguably had the more impressive ascents, each rising by the turn of the millennium from the status of impoverished, agriculture-oriented outpost of the Japanese empire to that of sovereign technology leader. While Taiwan has a panoply of success stories, TSMC is its economic (and strategic) crown jewel, and TSMC would not be the tech behemoth it is today if not for state involvement.
As Chris Miller explains in Chip War: The Fight for the World’s Most Critical Technology, TSMC’s origins can be traced to Taiwan’s Industrial Technology Research Institute (ITRI), a semigovernmental body that spent $650 million a year (adjusted for inflation) through the 1980s to seed enterprises to transform Taiwan’s economy. K. T. Li, who headed Taiwan’s finance ministry (among other agencies), is widely understood to be the architect of its seeding strategy and is credited with instilling a discerning culture trained upon utilizing publicly funded research to make new products for export. In 1982, Li told the New York Times, “We don’t have to produce everything, and it would be a mistake to try.”
In 1985, Li achieved one of the greatest personnel coups in industrial history, hiring Morris Chang, the man who would later found TSMC, to head ITRI. Li lured Chang, previously a C-suite executive at Texas Instruments and president of New York–based General Instrument, with something of a blank check. “We want a semiconductor industry in Taiwan,” Li said. “Tell me how much money you need.”
Two years thereafter, Chang went from granter to grantee, starting TSMC with investments from Taiwan’s government and from the Dutch electronics giant Philips. He brought to Taiwan decades of experience at the highest levels of America’s semiconductor industry and savvy insights on the globalized chip trade, leading to TSMC’s meteoric rise on the foundry model. “I knew what it took to do a fab well,” said Chang in 1994. “And I thought Taiwan possessed many of those requirements.” By 2000, TSMC was the leading high-end chip producer on the planet, Chang was hailed as the “Silicon Godfather,” and tiny Taiwan — erstwhile producer of Panama hats and Barbie dolls — was firmly established as a global tech heavyweight, presenting a story of industrial-policy success that now entrances the United States.
But Arizona, like the U.S. more broadly, is not East Asia, and attempts to replicate the economic template of the Four Little Dragons are ill-fated. The conditions and arrangements that made Taiwan a high-potential environment and subsequently turned it into a self-sustaining economic dynamo are its relatively low labor costs, streamlined access to government favoritism, a performance-focused economic culture, and strong human-capital indicators. That set of factors — we might call it “the Formosa Formula” — is less complete or lacking entirely on this side of the Pacific.
Labor costs are the top concern. In the mid 1980s, when Morris Chang moved to Taiwan, the island’s average household income was one-third that of the United States. While its pace of income growth has been higher than America’s in the four decades since, its household income remains at about half of the U.S. figure. American tech executive Kevin Xu, writing for Noema Magazine, argues that, if we compare the median salaries of software engineers, a U.S. worker is roughly three times more expensive than a Taiwanese worker — and that does not take into account health care and other employer-assumed costs of worker benefits, which can add another 25 percent to the cost per employee.
The second concern is America’s bureaucratic, regulatory, and public-funding culture when compared with the streamlined nature of Taiwan’s political system at the time of TSMC’s founding. As depicted by the historian Ezra Vogel, Taiwan’s “super-technocrats” such as K. T. Li were insulated from popular opinion and granted extraordinary latitude for decision-making. Through this political infrastructure, Chang had a direct line to the highest echelons of Taiwan’s then-authoritarian government, which pressured the island’s wealthiest tycoons to invest in TSMC. Taiwan would not hold fully democratic elections until 1992, five years after TSMC’s start.
The U.S., with its structure of government and political cleavages, does not have the same ability to guard industrial planning from fractious politics and competing interest groups. While Arizona may have “government, academia, and industry rowing in the same direction,” the real money is coming from a federal government beholden to inchoate ideological coalitions and subject to insidious public-choice dynamics.
Whereas Li was able to assiduously (some would argue with great luck) select state investment opportunities according to their performance capabilities, the Biden administration is complicating its own grant-making process. Rather than setting the ability to manufacture high-end chips as the primary criterion for CHIPS funding, the administration has given it a place of evaluative parity with factors such as engaging with labor unions, paying for workers’ child-care costs, and refraining from stock buybacks.
The CHIPS Act Notice of Funding Opportunity, issued by the Department of Commerce and the National Institute of Standards and Technology in February, is replete with progressive ideology. The funding rubric does not just “strive” for the inclusion of minority-owned businesses, veteran-owned businesses, women-owned businesses, and small businesses. It demands that funding applicants “explain how they will address this priority,” recommending the outlining of “proactive efforts” and “robust outreach plans.” The guidance even goes so far as to encourage the abandonment of economies of scale by divvying contracts into “smaller tasks or quantities to expand access to participation by minority-owned, veteran-owned, women-owned, and small businesses.”
The funding notice is in keeping with President Biden’s remarks at a CHIPS announcement ceremony last year, when he stipulated that “this bill has guardrails,” and that he would steer it “in the interest of the American workers, small businesses, and the communities.” He assured his coalition that CHIPS would require “working with small and minority-owned businesses” or else the federal government would “take back investments.”
Such onerous strictures do not a competitive chip make — a view TSMC’s Liu expressed before a Taiwanese industry group in April — but to have assumed that the process would be any different would be to ignore the realities of contemporary American political economy.
Largely beyond the control of the Biden administration, but perhaps even more costly, is the permitting web that ensnares new housing construction, new energy infrastructure, and indeed new semiconductor fabs across the United States. Eli Dourado, a fellow at the Center for Growth and Opportunity, says the U.S. permitting process leaves us with “one hand tied behind our backs” as we address global strategic challenges such as capacity in critical industries. The president of the chemical supplier Chang Chun, another Taiwanese company now doing business in Arizona, has said that, owing to U.S. regulations, building permits, and an insufficient supply of production materials, its factory construction was ten times costlier in the Grand Canyon State than back home. Taiwan gives TSMC and other companies a freedom to build that it simply will not have in the United States. Unless the urgent need for permitting reform is addressed, large-scale projects such as the one to which TSMC has committed itself will face a steep climb.
Human aspects, too, may hinder success. Shang-yi Chiang, who headed TSMC’s research-and-development department and also worked for American companies in Texas and California, is quoted in Miller’s book as saying that “people worked so much harder in Taiwan.” If something broke at 1 a.m. in America, the engineer would fix it the next morning, whereas at TSMC they’d fix it by 2 a.m. “They do not complain,” Chiang remarked, “and their spouse does not complain either.”
Perhaps compounding this issue are the United States’ comparatively poor performance markers for educational attainment. Taiwanese students — the next generation of workers — now far outstrip their American counterparts in math and science and are more able to perform high-skill jobs at companies such as TSMC. Taiwanese students notably excel in the OECD (Organisation for Economic Co-operation and Development) Programme for International Student Assessment (PISA), with Taiwan’s 15-year-olds scoring an average of 531 points in math (42 points above the OECD baseline), compared with America’s average of 478 (eleven points below it). In science, the numbers are less troubling from the U.S. perspective, with American students above the OECD baseline but still below Taiwan’s level. Arizona does not stand out from American education-performance norms. And while the U.S. is the world’s leader in university-level technology programs (TSMC’s own execs were educated here), Arizona’s universities are not prominent in the top tier. As economist Noah Smith has remarked, despite our universities and our sheer numerical advantage, the U.S. is not well positioned to produce the kind of broad-based technical workforce needed to staff the fabs and labs that power knowledge-based industries.
All in all, this means that costs in the U.S. are much higher than in Taiwan, particularly relative to the quality of output. In November 2022, Morris Chang estimated that production in Arizona would be 55 percent higher than in Taiwan, but TSMC’s fourth-quarter earnings report indicates that simply building fabs in Arizona could be as much as five times more expensive than it would be in Taiwan.
Asked on the earnings call to explain the discrepancy between Taiwan and the U.S., Wendell Huang, TSMC’s chief financial officer, elaborated on that theme:
We’re not able to share with you a specific cost-gap number between Taiwan and [the] U.S., but we can share with you that the major reason for the cost gap is the construction cost of building and facilities, which can be four to five times greater for [a] U.S. fab versus a fab in Taiwan. The high cost of construction includes labor cost, cost of permits, cost of occupational safety and health regulations, inflationary costs in recent years, and people and learning-curve costs.
Just three months after President Biden, Senator Kelly, and Mr. Chang toasted to co-prosperity, Chang, too, poured cold water on the economic outlook of the Arizona plan. At a March event in Taipei, he conceded that the Arizona project is an economic loser. Even aside from the astronomical building costs explained by Huang, the cost of producing chips in Arizona could be as much as 100 percent higher than the cost of producing the same chips in Taiwan, Chang now says. Amid these discoveries, John Liu and Paul Mozur of the New York Times report that internal doubts are mounting among the company’s rank and file as well, as employees express concern that the Arizona project could distract from TSMC’s research-and-development focus.
For the global economy, of which the U.S. will still be a part even if high-end chip manufacturing were to take place domestically, that represents a painful loss. “When the cost goes up, the pervasiveness of chips will either stop or slow down considerably,” Chang cautioned. While he has expressed his support for America’s drive to outcompete China, the Taipei Times reported in April that he has now fully soured on CHIPS, calling it a “very expensive exercise in futility.”
Two thousand miles to Arizona’s northeast, Wisconsin finds itself mired in a failed effort of its own to capture a bit of the Formosa Formula magic — perhaps a harbinger of what may lie ahead in the TSMC saga. Inducements granted by the state to Taiwan’s Foxconn Technology Group delivered almost none of the promised outcomes, as George Mason University researchers Matthew D. Mitchell, Michael D. Farren, Jeremy Horpedahl, and Olivia Gonzalez explained in their 2019 study “The Economics of a Targeted Economic Development Subsidy.”
In a precursor to the Arizona song-and-dance, Foxconn chairman Terry Gou joined Governor Scott Walker of Wisconsin, House Speaker Paul Ryan, and President Donald Trump at the White House in July 2017 to sign a deal giving the company $3.6 billion in cash subsidies and other benefits, to be paid out over 15 years in exchange for a commitment to invest $10 billion and employ 13,000 Wisconsinites to manufacture large LCD screens for TVs. Soon, however, Foxconn began a retreat from the plan, opting to build, instead of the large LCD Generation 10.5 plant that Wisconsin wanted, a Generation 6 facility to make smaller LCDs for devices such as tablets, mobile phones, and smart watches. Louis Woo, special assistant to Foxconn’s CEO, told Reuters in 2019 that labor expenses in the United States made large-TV construction cost-prohibitive. By late 2020, the company had hired less than a quarter of the workers it was expected to employ at that point and had invested less than 10 percent of the expected sum.
“In terms of TV, we have no place in the U.S.,” Woo said. “We can’t compete.” The lower-grade plant, the George Mason researchers conclude, reduced expected positive knock-on effects for Wisconsin by 75 percent.
While industrial-policy boosters will deride the George Mason study as “free-market fundamentalism,” libertarian academics are not alone in taking a dim view of Wisconsin’s industrial-policy experiment. The Peterson Institute for International Economics (PIIE), for example, included the Foxconn deal among its poorer performers in a 2021 analysis of 18 American industrial-policy episodes over the past 50 years.
Noting that U.S. tech firms often do pathbreaking research and development within the United States while relying on foreign suppliers for production expertise, PIIE is careful to distinguish between basic public research funding and the targeted production subsidies that the Wisconsin and CHIPS examples represent. Wisconsin, PIIE writes, “succeeded in creating local jobs at a reasonable cost per job-year,” but “most of the jobs created in the subsidizing state probably came at the expense of jobs that might have been created in rival states, and quite possibly at the expense of alternative jobs in the home state.” The tepid jobs outcome, graded a B by PIIE, was its bright spot. As an effort to make Wisconsin’s industry competitive in international markets, the deal earned a C; as an effort to advance the technological frontier, a D.
If the Wisconsin case is a guide, what Senator Mark Kelly envisions as a global hub for microelectronics is more likely to become an Arizona albatross.
From the national perspective, the CHIPS Act represents a left–right policy convergence that has laundered the once-in-a-century, pandemic-induced semiconductor-demand shock and starched it with a debate-quashing invocation of national security, all in order to enact a preexisting Made in America economic agenda at odds not only with our prosperity but with our security as well. The position advanced by President Biden, Representative Ro Khanna (D., Calif.), and others is that semiconductor-manufacturing subsidies will revitalize the American dream. This view does not square with the realities of a global semiconductor market in which America still plays a starring role.
Overlooked is that the U.S. accounts for about half of global semiconductor revenues, given its status as the world’s leader in lucrative chip design and commercialization. While TSMC and South Korea’s Samsung are the top manufacturers, the top designers are America’s Qualcomm and Nvidia. The U.S. also still produces more than half of the world’s output in some microelectronic subcategories. To maximize American prosperity, we should lean into these advantages, not attempt to claw back a segment of the industry in which comparative advantage now lies elsewhere.
With the CHIPS Act and state-based industrial policies such as Arizona’s, we are at risk of following investment, not leading it. The once-in-a-century chip shortage that drove up the cost of cars in the wake of the pandemic elicited massive private investment, including tentative investments from TSMC and Samsung in the United States. Meanwhile, demand has leveled off, leaving even mighty TSMC facing an annual revenue decline in 2023. The new American subsidies are pouring money into an industry that is more likely to see surpluses than shortages in the coming years.
Moreover, to undo economic ties across the Pacific would be to weaken our security footing. An underlying impetus for our industrial policy is to stay ahead of China, but CHIPS, in conjunction with the Inflation Reduction Act (IRA), bolsters China’s aims of degrading American alliances and trade systems. While the IRA erects barriers to products such as Korean cars, the CHIPS Act has sparked a subsidy race to the bottom. Elbridge Colby, a former deputy assistant secretary of defense, argues that if we raise the economic drawbridges in this way, we risk isolating the U.S. from this century’s strongest economic region and reducing incentives in Asia to counter China.
The alternative is to marginalize China from an otherwise free-trading system that respects comparative advantage and makes all of its participants better off.
Japan, Taiwan, and South Korea, our three strategic partners in Northeast Asia, will benefit from our continued economic engagement and will return that benefit in the form of the affordable exports they supply to the U.S. The White House noted in its 2021 supply-chain report that Taiwan and South Korea heavily subsidize their industries to this day, but, as the TSMC figures are beginning to show, production here in the U.S. will still be less competitive. According to Boston Consulting Group, only half of the discrepancy in cost can be attributed to subsidies in those places — and that is in comparison with a best-case cost scenario stateside.
Some will argue that Japan and South Korea are driven by their own strategic considerations to align against China despite these U.S. actions to undermine trade in the Pacific. That may be so, but the same cannot be said of the emerging economies of South and Southeast Asia that are larger by population, poised for an economic surge, and willing to consider China their partner in that pursuit. Chief among them is Indonesia, an archipelago with the world’s fourth-largest population and some of its largest deposits of key global commodities.
One national-security argument for reshoring chipmaking remains: that China might seek to take Taiwan by force and thereby cut the U.S. off not only from commercial inputs but from semiconductors that are vital for our advanced defense systems. In 2021, Admiral Philip Davidson, commander in the Indo-Pacific at the time, testified before the Senate Armed Forces Committee that the threat of Chinese action against Taiwan would be “manifest during this decade, in fact in the next six years.” But to hedge against that near-term threat with the CHIPS Act is a fool’s errand.
While the specific chip needs of the Defense Department are closely guarded secrets, it is widely understood that, because the cutting edge of the semiconductor industry is being pushed forward by commercial applications, the Pentagon finds itself chasing after the best technology these days rather than driving the industry as it did in its infancy. It would surely bolster our national defense to have the Pentagon’s chip needs met with domestic manufacturing, but the fast-moving nature of the industry and the scale of investment required to remain at the cutting edge mean that even with the CHIPS Act in place, TSMC’s emerging processes are likely to remain in Taiwan, where it has its strongest production ecosystem. That the U.S. is in this position with respect to advanced chips despite the Defense Department’s launching of the Trusted Foundry Program in 2003 demonstrates the challenge of driving 21st-century technology through procurement. After 20 years, the Pentagon gets only 2 percent of its chips from foundries in the program.
Given the nature of TSMC’s manufacturing, an outcome similar to that of the Foxconn investment in Wisconsin is likely: TSMC will produce many chips in Arizona but continue to advance its cutting-edge production elsewhere for cost reasons, leaving Arizona as a legacy producer and leaving our military in the same position of foreign dependency a decade hence. Discomfiting though that is, the defense apparatuses of our rivals find themselves in an even worse position, chasing the best commercial technology while the Biden administration’s export controls choke them off from it.
In aiming for “global hub” status, Arizona has thus set itself up for disappointment. The insight that policy success depends on prevailing conditions should warn us against any attempt to graft the outline of Taiwan’s industrial policy tale, alluring though it is, onto our markedly different system. From the American vantage point, Wisconsin and Arizona bear little resemblance, but they exist in the same national economic and political environment, giving rise to Morris Chang’s snowballing pessimism. And although the TSMC investment will create some local jobs, the opportunity cost will be jobs in other states or other industries while Arizona still remains behind the technological frontier.
To the extent that Arizona does receive a durable economic benefit, it will be due not to targeted support for the semiconductor industry but to the state’s business-friendly posture and existing network effects, conditions that predate the post-pandemic chips panic. Kirk Adams, who was speaker of the Arizona house of representatives and later chief of staff to Governor Ducey, shed light on those longer-standing conditions, which conduce to longer-standing success. “For more than a decade Arizona has been laying the groundwork for large scale manufacturing,” Adams wrote in an email. “It began in 2011 with the passage of the Jobs Bill, a bill that lowered taxes for corporations, and specifically manufacturing.” While Adams does indicate the state’s tilt toward making things at home, he explains that neither that nor the CHIPS Act will be decisive for Arizona to succeed. Rather, success will depend on “the basic spade work of reducing the cost of capital and other pro-growth public policy.”
Arizona can hardly be faulted for sensing the political winds and attempting to put federal largess to productive use. It deserves credit for the market-oriented elements of its approach. But, lacking the Formosa Formula, it is likely to find modest success at best, and that success will come at a net cost to the country as a whole. The promises of President Biden’s CHIPS Act — job creation, price reduction, economic growth, and strengthened national security — will remain unfulfilled.
Jordan McGillis is a Paulson Policy Analyst at the Manhattan Institute. Clay Robinson is a graduate student at Arizona State University’s Thunderbird School of Global Management.







Comments